
Quarterly Financial Report for the quarter ended December 31, 2023
1.0 Introduction
This quarterly financial report should be read in conjunction with the Main Estimates and Supplementary Estimates. It has been prepared by Canadian Grain Commission (CGC) management as required by section 65.1 of the Financial Administration Act and is in the form and manner prescribed by the Treasury Board. This quarterly report has not been subject to an external audit or review.
1.1 Authority, mandate and program activities
The CGC was established in 1912 and is the federal government department responsible for administering the provisions of the Canada Grain Act (CGA).
The CGC’s mandate as set out in the act is to, “in the interests of the grain producers, establish and maintain standards of quality for Canadian grain and regulate grain handling in Canada, to ensure a dependable commodity for domestic and export markets”.
The CGC’s vision is “To be a world class, science-based quality assurance provider”. The Minister of Agriculture and Agri-Food is responsible for the CGC.
The CGC’s Core Responsibility is Grain Regulation, or, to regulate grain handling in Canada and to establish and maintain science based standards for Canadian grain. The Commission regulates the handling of 21 grainsFootnote 1 grown in Canada to protect producer rights and to ensure the integrity of grain transactions.
The CGC’s Departmental Results are that domestic and international markets regard Canadian grain as dependable and safe, and that farmers are fairly compensated for their grain. The CGC has three programs: Grain Quality, Grain Research and Safeguards for Grain Farmers. Internal Services supports these programs.
Further details on the CGC’s authority, mandate, and programs may be found in the Departmental Plan, the Departmental Results Report, and the Main Estimates.
1.2 Basis of presentation
This quarterly report has been prepared by management using an expenditure basis of accounting (modified cash) and a special purpose financial reporting framework designed to meet financial information needs with respect to the use of spending authorities. The accompanying Statement of Budgetary Authorities compares the department’s spending authorities granted by Parliament to those used by the department. Information in the Statement of Authorities is consistent with that in the Main Estimates and Supplementary Estimates.
The authority of Parliament is required before moneys can be spent by the Government. Approvals are given in the form of annually approved limits through Appropriations Acts or through legislation in the form of statutory spending for specific purposes.
As part of the Parliamentary business of supply, the Main Estimates must be tabled in Parliament on or before March 1 preceding the new fiscal year.
The CGC uses the full accrual method of accounting to prepare and present its annual departmental financial statements included in the Departmental Results Report. However, the spending authorities voted by Parliament are on an expenditure basis (modified cash) of accounting.
1.3 Canadian Grain Commission financial structure
The CGC’s funding structure is based on budgetary authorities that are comprised of both statutory and voted (non-statutory) authorities. The statutory authorities include employee benefit plan authority for appropriation-funded personnel costs and CGC revolving fund authority which allows re-spending of fees collected. The voted authority is Vote 1 – Appropriation including Ad hoc which includes annual appropriation authority and any one-time ad hoc appropriation authority for the fiscal year. The CGC aims to recover, on average, approximately 90% of costs through fees and the balance through appropriation.
The CGC’s revenue is mainly based on grain volumes inspected and weighed, which can fluctuate from year-to-year due to external factors as described in 3.1 Revenue Uncertainty. Significant variances can arise between projected and actual revenues since grain volumes are estimated based on historical averages while operational costs are relatively fixed. The baseline for existing service and licence fees were established and implemented in 2017-18 based on a $62.49 million budget and annual average official inspection and weighing volumes of 34.4 million metric tonnes.
From 2013-14 through 2020-21, the CGC accumulated surpluses due to grain sector increases in grain production and utilization of enhanced technology. In 2020-21, the CGC updated its model for forecasting and effective August 1, 2021, fees were reduced by 29% and realigned with an average grain volume forecast of 48.1 million metric tonnes.
Subsequently, drought conditions across western Canada in 2021 significantly decreased grain production yields. This resulted in lower-than-anticipated grain volumes at export position of 32.6 million metric tonnes in 2021-22 and 38.0 million metric tonnes in 2022-23. The CGC used its position as a revolving fund to draw down on accumulated surplus and cover the revenue shortfalls of $21.79 million for both fiscal years. This does not include strategic investment framework spending.
The CGC is finalizing a review of its revenues, costs, grain volume forecasting model, and service standards. The purpose of the review is to ensure fees remain aligned with the cost of providing services into the future and that service standards continue to meet the grain sector’s needs.
The CGC’s revenue projections for 2024-25 and beyond are based on the funding model identified in the 2017 User Fees Consultation and Pre-Proposal Notification, fees published in the Canada Gazette, Part II in March 2018, and updated fees published in the Canada Gazette, Part II in July 2021. Since the 2019-20 fiscal year, the CGC has adjusted fees annually for inflation on April 1. The 2024-25 fee adjustment is based on the April All-Items Consumer Index for Canada of 4.4%. Current fee amounts are located on grainscanada.gc.ca.
Planned revenue projections and full time equivalents (FTEs) for 2023-24 and beyond are available in the CGC’s 2023-24 Departmental Plan.
2.0 Highlights of fiscal year to date
This section highlights any significant items that affected the year-to-date results and/or contributed to the net change in resources available for the year and actual expenditures. It should be read in conjunction with the Statement of Budgetary Authorities and the Departmental Budgetary Expenditures by Standard Object, which can be found at the end of this report.
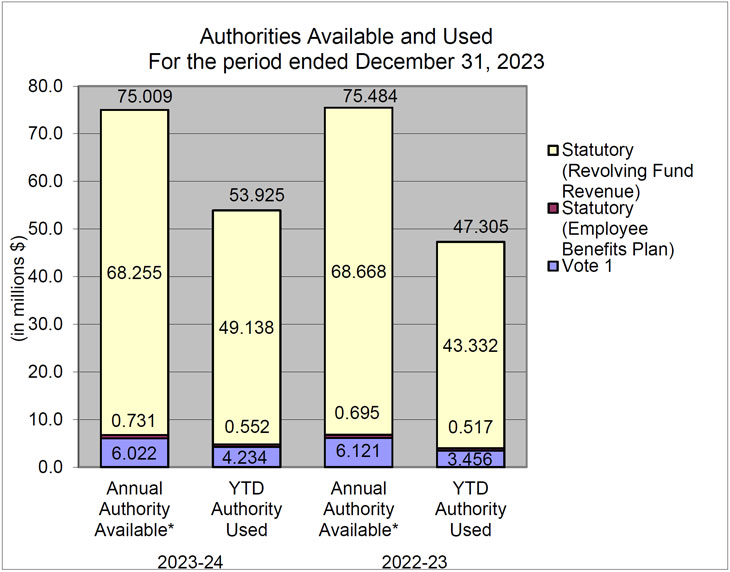
Details
| 2023 to 2024 | 2022 to 2023 | |||
|---|---|---|---|---|
| Annual Authority Available* | YTD Authority Used | Annual Authority Available* | YTD Authority Used | |
| Vote 1 | 6.022 | 4.234 | 6.121 | 3.456 |
| Statutory (Employee Benefits Plan) | 0.731 | 0.552 | 0.695 | 0.517 |
| Statutory (Revolving Fund Revenue) | 68.255 | 49.138 | 68.668 | 43.332 |
| Total | 75.009 | 53.925 | 75.484 | 47.305 |
| * Authority available based on amounts approved through the Estimates process. Amounts detailed in Statement of Authorities. | ||||
2.1 Authority available analysis
As reflected in the Statement of Budgetary Authorities, the department’s total budgetary authority available for use (net of Revolving Fund revenue) in the fiscal year as at December 31, 2023, is $9.377 million, as compared to $14.032 million as at December 31, 2022. The decrease in authority of $4.655 million is primarily due to anticipated increased revenues as a result of drought recovery and focused spending on key strategic initiatives.
2.2 Authority used analysis
As reflected in the Departmental Budgetary Expenditures by Standard Object, the department’s total net budgetary expenditures used during the quarter ended December 31, 2023, is $8.799 million, as compared to $5.208 million as at the quarter ended December 31, 2022. The change of $3.591 million in total net budgetary expenditures used can be attributed to the following:
- The net increase of $0.059 million in revolving fund revenues received is primarily due to consistent market export demand as compared to the same period in prior year.
- The overall increase of $3.532 million in gross budgetary expenditures is a result of the following variances:
- The net increase of $3.081 million in expenditures for personnel is primarily due to salary increases from collective agreement bargaining resulting in retroactive and one-time lump sum payments.
- The net increase of $0.269 million in professional and special services is primarily due to enhancements to enterprise resource planning software and timing of legal services payment processing.
- The net increase of $0.212 million in rentals is primarily due to timing of renewal payments for ongoing information technology licensing fees and new unified enterprise support services.
The department’s total net budgetary expenditures used year-to-date at quarter ended December 31, 2023, is $20.136 million, as compared to $22.604 million for the same period last year. The change of $2.468 million in total net budgetary expenditures used year-to-date can be attributed to:
- The net increase of $9.088 million in revolving fund revenues received is primarily due to a return to more typical grain volumes as drought recovery continues.
- The overall increase of $6.620 million in gross budgetary expenditures is a result of the following variances:
- The net increase of $6.104 million in expenditures for personnel is primarily due to salary increases from collective agreement bargaining resulting in retroactive and one-time lump sum payments.
- The net increase of $0.258 million in rentals is primarily due to inflation and timing of rental cost allocations.
3.0 Risks and uncertainties
Risk management is an essential part of strategic planning and decision making at the CGC. The CGC has an established process to identify, monitor, mitigate and manage corporate level risk. As identified in the 2023-24 Departmental plan, the top corporate risks that could affect achieving planned results under the CGC’s Core Responsibility are:
- the capacity to respond to opportunities and evolving sector needs due to resource constraints
- the ability to attract and/or retain a skilled workforce
To mitigate program risk and ensure long-term success in delivering the departmental results, the CGC will work to deliver on its strategic plan as described in the “Plans at a glance” and the “Core responsibility: planned results and resources, and key risks” sections of CGC’s 2023-24 Departmental Plan.
A significant risk to the CGC’s financial plan for fiscal year 2023-24 is revenue uncertainty due to grain volumes, which are not fully known prior to the commencement of the fiscal year. The CGC is reviewing its annual grain volume forecast as part of the organization’s comprehensive fee review. The CGC has found that the organization is inspecting and weighing lower-than-anticipated grain volumes compared to the forecasted volume of 48.1 million metric tonnes that was used to adjust fees in 2021. As of December 2023, the CGC is forecasting to inspect and weigh 42.0 million metric tonnes of grain annually going forward. The lower forecast indicates that the CGC’s operations may not be cost recovered for the 2023-24 fiscal year without a change in the forecast’s trajectory. This will result in drawing on the CGC’s accumulated surplus in 2023-24 and likely in future years as well. While the CGC maintains a substantial accumulated surplus, there is a risk that the organization may not be able to adjust its fees to ensure that its fees cover the costs of providing services.
Expected 2023-24 financial risks associated with the CGA Review and the CGC’s accumulated surplus are minimal. However, the CGA Review and decisions on the CGC’s accumulated surplus could impact the CGC’s financial plan in future fiscal years.
3.1 Revenue uncertainty
CGC fee revenue is largely based on grain volumes which fluctuate from year-to-year. Grain volumes are not fully known prior to commencement of the fiscal year which can result in significant variances between CGC projected and actual revenues. The CGC could accumulate surpluses (shown as unused authority carried forward in Public Accounts) in years with higher-than-average grain volumes and may be required to draw down on its accumulated surplus funds in years with lower-than-average volumes.
Climate change and extreme weather events, such as droughts and floods, can significantly impact grain production and consequently increase the CGC’s revenue risk. The Canadian grain sector continually faces export volume uncertainty regarding access to international markets due to market sensitivity to actual or perceived grain quality and food-safety issues. Restricted market access has the potential to result in lower-than-expected grain volumes and revenues.
Excessively hot and dry growing conditions across most of the western Canadian grain production area in 2021 resulted in significantly decreased yields and caused reduced grain volumes at export position in the latter half of 2021-22. The reduced volume of grain inspected and weighed by the CGC in fiscal year 2021-22 resulted in a need to use $7.356 million of surplus funds.
Grain production returned to expected levels in 2022, allowing for exports to increase in the last half of the fiscal year. However, throughout 2022-23, the volume of grain inspected and weighed by the CGC was lower than the forecast due to the carryover effects of the 2021 drought on export volumes. This, coupled with the lower fees that came into effect on August 1, 2021, contributed to a need for use of $14.431 million in surplus funds.
Though not as low as the 2021 drought year, grain production in 2023 is expected to be lower than production in 2022 by 7.5% and 2.2% lower than the 2018-22 production average. The CGC’s annual budget is reviewed throughout the year to accommodate shifting needs and priorities, including risk mitigation strategies that enable the CGC to accommodate up to a 20% variance in forecasted grain volumes. The CGC will continue to monitor and assess impacts and uncertainties associated with grain volumes and the potential impact on 2023-24 revenues.
3.2 Surplus and Canada Grain Act Review
From 2013 to 2018, unprecedented increases in Canadian grain production and relatively stable operating costs led to an accumulated revolving fund surplus of approximately $130.7 million by March 31, 2018. As reported in the 2022-23 Public Accounts of Canada, the CGC’s total surplus balance is $130.3 million as of March 31, 2023.
In 2018, the CGC established an Investment Framework focused on strategic investments in three key areas:
- strengthening safeguards for producers,
- investing in grain quality assurance, and
- enhancing grain quality science and innovation.
The Investment Framework committed $90 million of the accumulated surplus for strategic investments, while retaining $40 million for a contingency operating reserve to mitigate risks associated with declines in revenues. When the Investment Framework was announced in 2018, the CGC envisioned rolling out investments over a two-year timeframe. However, this timeline was subsequently delayed because of Budget 2019’s announcement of the CGA Review to ensure alignment between the two processes.
From 2018 to 2021, Canadian grain export volumes continued to grow and some of the factors leading to recent increases were not anticipated by the current grain forecasting model. Combined with relatively stable operating costs, this led to further surplus growth in 2018 to 2021, the majority of which occurred in 2020-21 due to extraordinary grain export volumes. Prior to 2020-21, the CGC net relatively small surpluses which are typical in a revolving fund environment. The CGC addressed this situation and mitigated the risk of further surplus growth through updates to its annual grain volumes and revenue projections model and the August 1, 2021, fee adjustments as described in 1.3 CGC Financial Structure.
After being paused for much of 2020-21 due to the COVID-19 pandemic, Agriculture and Agri-Food Canada (AAFC) formally relaunched the CGA Review in January 2021 with public consultations closing on April 30, 2021. A resulting “What We Heard” report was published in August 2021 detailing consultation feedback. The CGC provided technical and policy support to AAFC through evidence-based analysis and advice for a modernized regulatory framework. Potential impacts of the CGA Review on the CGC’s funding model and accumulated surplus are unknown at this time. Going forward, the CGC will consider investment initiatives within the broader context of the CGC’s strategic plan, modernization initiatives, and the CGA Review outcomes and any impacts of grain volumes on fee revenue.
The CGC continues to position itself as a global leader in grain science and has developed options for investments that will ensure organizational capacity to provide innovative and science-based programs and services. To ensure the Grain Research Lab functions efficiently until a new location is identified, the CGC has developed a five-year investment plan to make required improvements to maintain and improve research capacity.
To date, the CGC has allocated Investment Framework funding to the following projects:
- enhancements to the Harvest Sample Program;
- grain research laboratory renewal, upgrades, and maintenance of infrastructure to deliver science programming essential to CGC’s mandate; and
- the MyCGC e-services platform, a suite of integrated program delivery systems to provide seamless digital service to CGC clients.
4.0 Significant changes to operations, personnel and programs
In June 2022, the CGC updated its strategic plan for fiscal year 2023-24 and beyond. While most CGC resources will continue to be dedicated to day-to-day delivery of programs and services, the remainder will be dedicated to modernizing the CGC through the following four areas of focus:
- Modernize the CGC’s regulatory framework, programs, and services;
- Position the CGC as a global leader in grain science;
- Strengthen the CGC’s stakeholder relationships, with a focus on Canadian grain producers; and
- Attract and retain employees in a competitive market.
For updated information on the CGC’s strategic plan, see the “Plans at a glance” and the “Core responsibility: planned results and resources, and key risks” sections of CGC’s 2023-24 Departmental Plan.
Doug Chorney’s term as Chief Commissioner was extended on December 18, 2023, to April 30, 2024. This extension will provide the Government of Canada the time to complete an open, transparent, and merit-based selection process.
The Government of Canada is committed to using selection processes to fill Governor in Council positions, including for appointments and reappointments.
Approval by Senior Official
Approved by:
Doug Chorney
Chief Commissioner
Winnipeg, Manitoba
February 22, 2023
Cheryl Blahey
Chief Financial Officer
Winnipeg, Manitoba
February 17, 2023
Statements of budgetary authorities (unaudited)
| Fiscal Year 2023-24 | Fiscal Year 2022-23 | |||||
|---|---|---|---|---|---|---|
| (in thousands of dollars) | Total available for use for the year ending March 31, 2024 | Used during the quarter ended December 31, 2023 | Year-to date used at quarter end | Total available for use for the year ending March 31, 2023 | Used during the quarter ended December 31, 2022 | Year-to date used at quarter end |
| Vote 1 | ||||||
| Appropriation including Ad hoc | $ 6,022 | 1,383 | 4,234 | $ 6,121 | 1,110 | 3,456 |
| Statutory Authorities: | ||||||
| Revolving Fund Gross Expenditures | 68,255 | 18,655 | 49,138 | 68,668 | 15,410 | 43,332 |
| Revolving Fund Gross Revenues | (65,631) | (11,418) | (33,789) | (61,452) | (11,477) | (24,701) |
| Revolving Fund Net Expenditures | $ 2,624 | 7,236 | 15,349 | $ 7,215 | 3,933 | 18,631 |
| Employee Benefit Plan | 731 | 180 | 552 | 695 | 165 | 517 |
| Total Statutory Authorities | 3,355 | 7,416 | 15,902 | 7,911 | 4,098 | 19,148 |
| Total Budgetary Authorities | $ 9,377 | 8,799 | 20,136 | $ 14,032 | 5,208 | 22,604 |
| Due to rounding, totals may not add to totals shown. | ||||||
Departmental budgetary expenditures by standard object (unaudited)
| Fiscal Year 2023-24 | Fiscal Year 2022-23 | |||||
|---|---|---|---|---|---|---|
| (in thousands of dollars) | Planned Expenditures for the year ending March 31, 2024* | Expended during the quarter ended December 31, 2023 | Year-to date used at quarter end | Planned Expenditures for the year ending March 31, 2023* | Expended during the quarter ended December 31, 2022 | Year-to date used at quarter end |
| Expenditures: | ||||||
| Personnel | 50,766 | 15,434 | 41,986 | 47,286 | 12,353 | 35,882 |
| Transportation and communications | 2,745 | 919 | 1,866 | 2,477 | 1,001 | 1,712 |
| Information | 366 | 40 | 114 | 618 | 76 | 164 |
| Professional and special services | 4,026 | 1,304 | 2,018 | 6,243 | 1,035 | 1,933 |
| Rentals | 7,558 | 1,504 | 4,555 | 7,220 | 1,292 | 4,297 |
| Repair and Maintenance | 2,379 | 282 | 1,245 | 2,684 | 482 | 1,099 |
| Utilities, materials and supplies | 1,882 | 321 | 866 | 2,065 | 158 | 748 |
| Acquisition of machinery and equipment | 5,287 | 438 | 1,305 | 6,891 | 290 | 1,483 |
| Other Subsidies and payments | - | (26) | (32) | - | (2) | (13) |
| Total Gross Budgetary Expenditures | $ 75,009 | 20,217 | 53,925 | $ 75,484 | 16,685 | 47,305 |
| Revolving Fund Revenue (To be credited to Vote) | (65,631) | (11,418) | (33,789) | (61,452) | (11,477) | (24,701) |
| Total Net Budgetary Expenditures | $ 9,377 | 8,799 | 20,136 | $ 14,032 | 5,208 | 22,604 |
| * Due to rounding, totals may not add to totals shown. | ||||||