
The Fiscal Monitor - July 2026
Highlights
July 2026
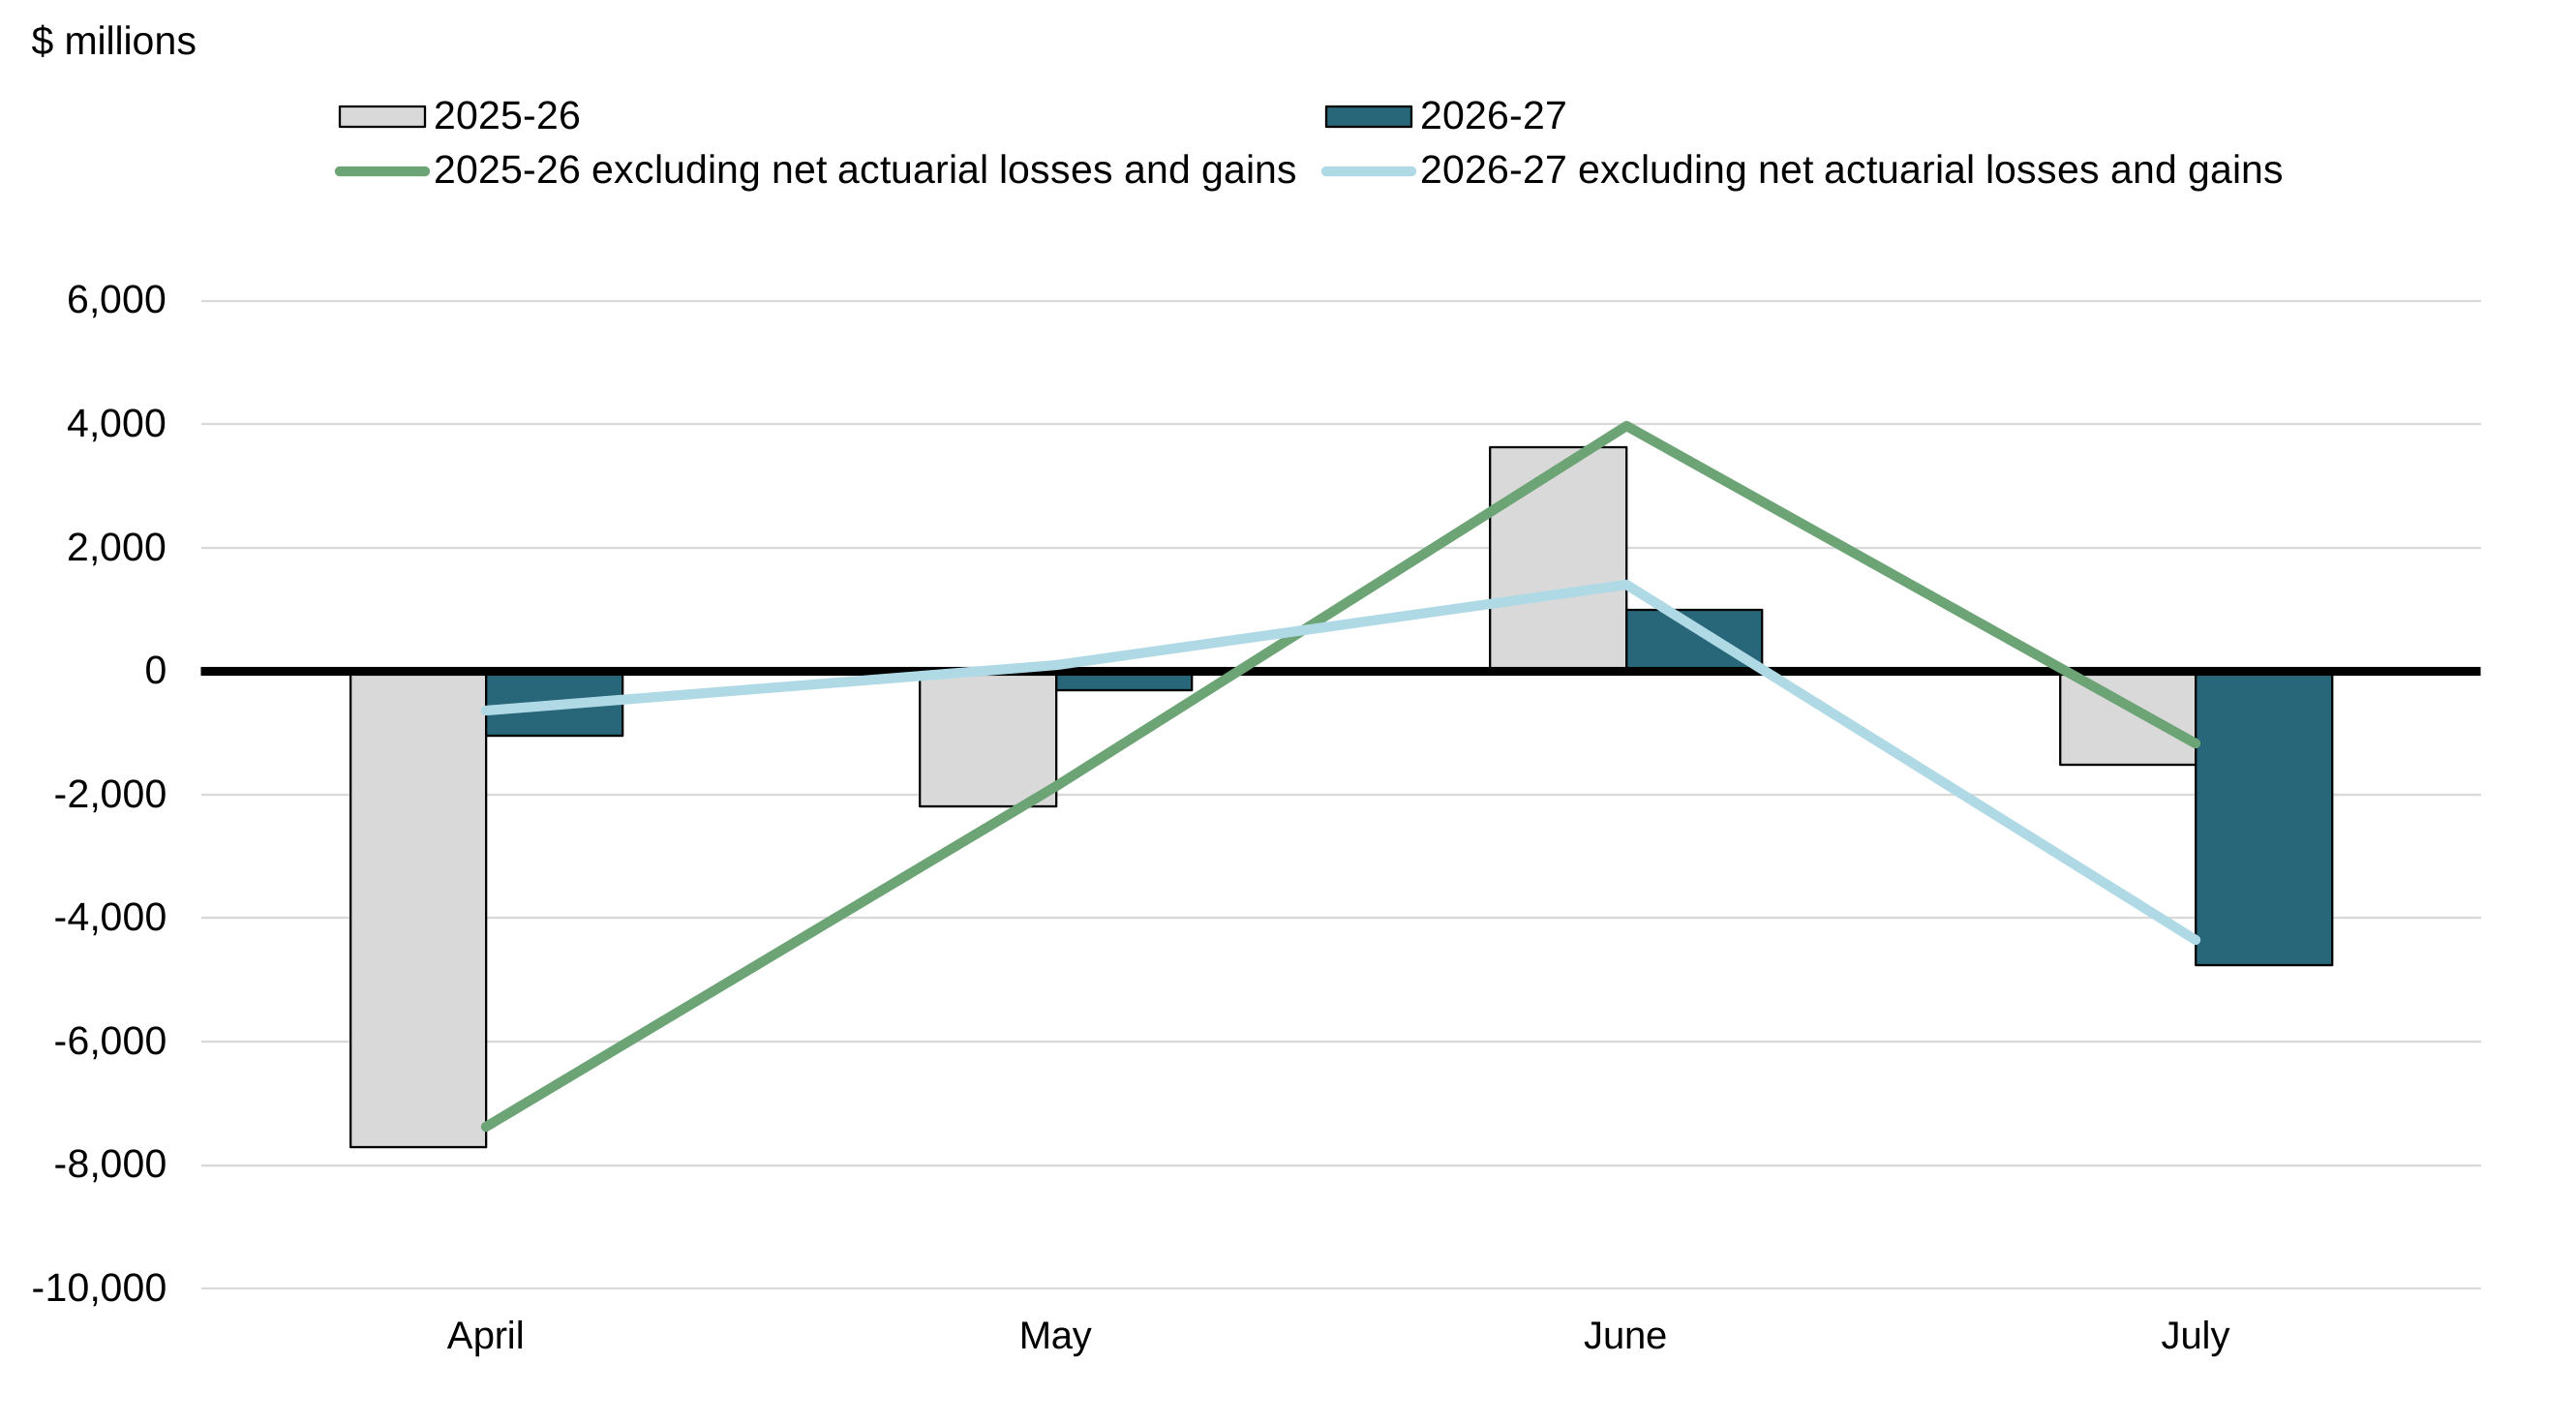
There was a budgetary deficit of $4.8 billion in July 2026, compared to a deficit of $1.5 billion in July 2025. The budgetary deficit before net actuarial losses and gains was $4.4 billion, compared to a deficit of $1.2 billion in the same period of 2025-26. The budgetary balance before net actuarial losses and gains is intended to supplement the traditional budgetary balance and improve the transparency of the government's financial reporting by isolating the impact of the amortization of net actuarial losses and gains arising from the revaluation of the government's pension and other employee future benefit plans.
Monthly Budgetary Balance and Budgetary Balance Excluding Net Actuarial Losses and Gains
Compared to July 2025:
- Revenues increased by $0.2 billion, or 0.5 per cent, largely reflecting higher personal income tax revenues, other revenues and Goods and Services Tax (GST) revenues. These increases were partially offset by lower corporate income tax revenues, customs import duties and energy tax revenues.
- Program expenses excluding net actuarial losses were up $2.8 billion, or 7.3 per cent, reflecting higher direct program expenses, major transfers to provinces, territories and municipalities, and major transfers to persons.
- Public debt charges were up $0.5 billion, or 11.3 per cent, as the impact of higher average effective interest rates on an increased stock of marketable bonds and higher Consumer Price Index adjustments on Real Return Bonds was offset in part by lower interest rates on treasury bills.
- Net actuarial losses were up $0.1 billion, or 23.9 per cent, reflecting the amortization of losses arising from actuarial valuations of the government's pension and other employee future benefit plans prepared for the Public Accounts of Canada 2025, which began partway through 2025-26, offset in part by the end of the amortization of certain prior years' net actuarial losses.
April to July 2026
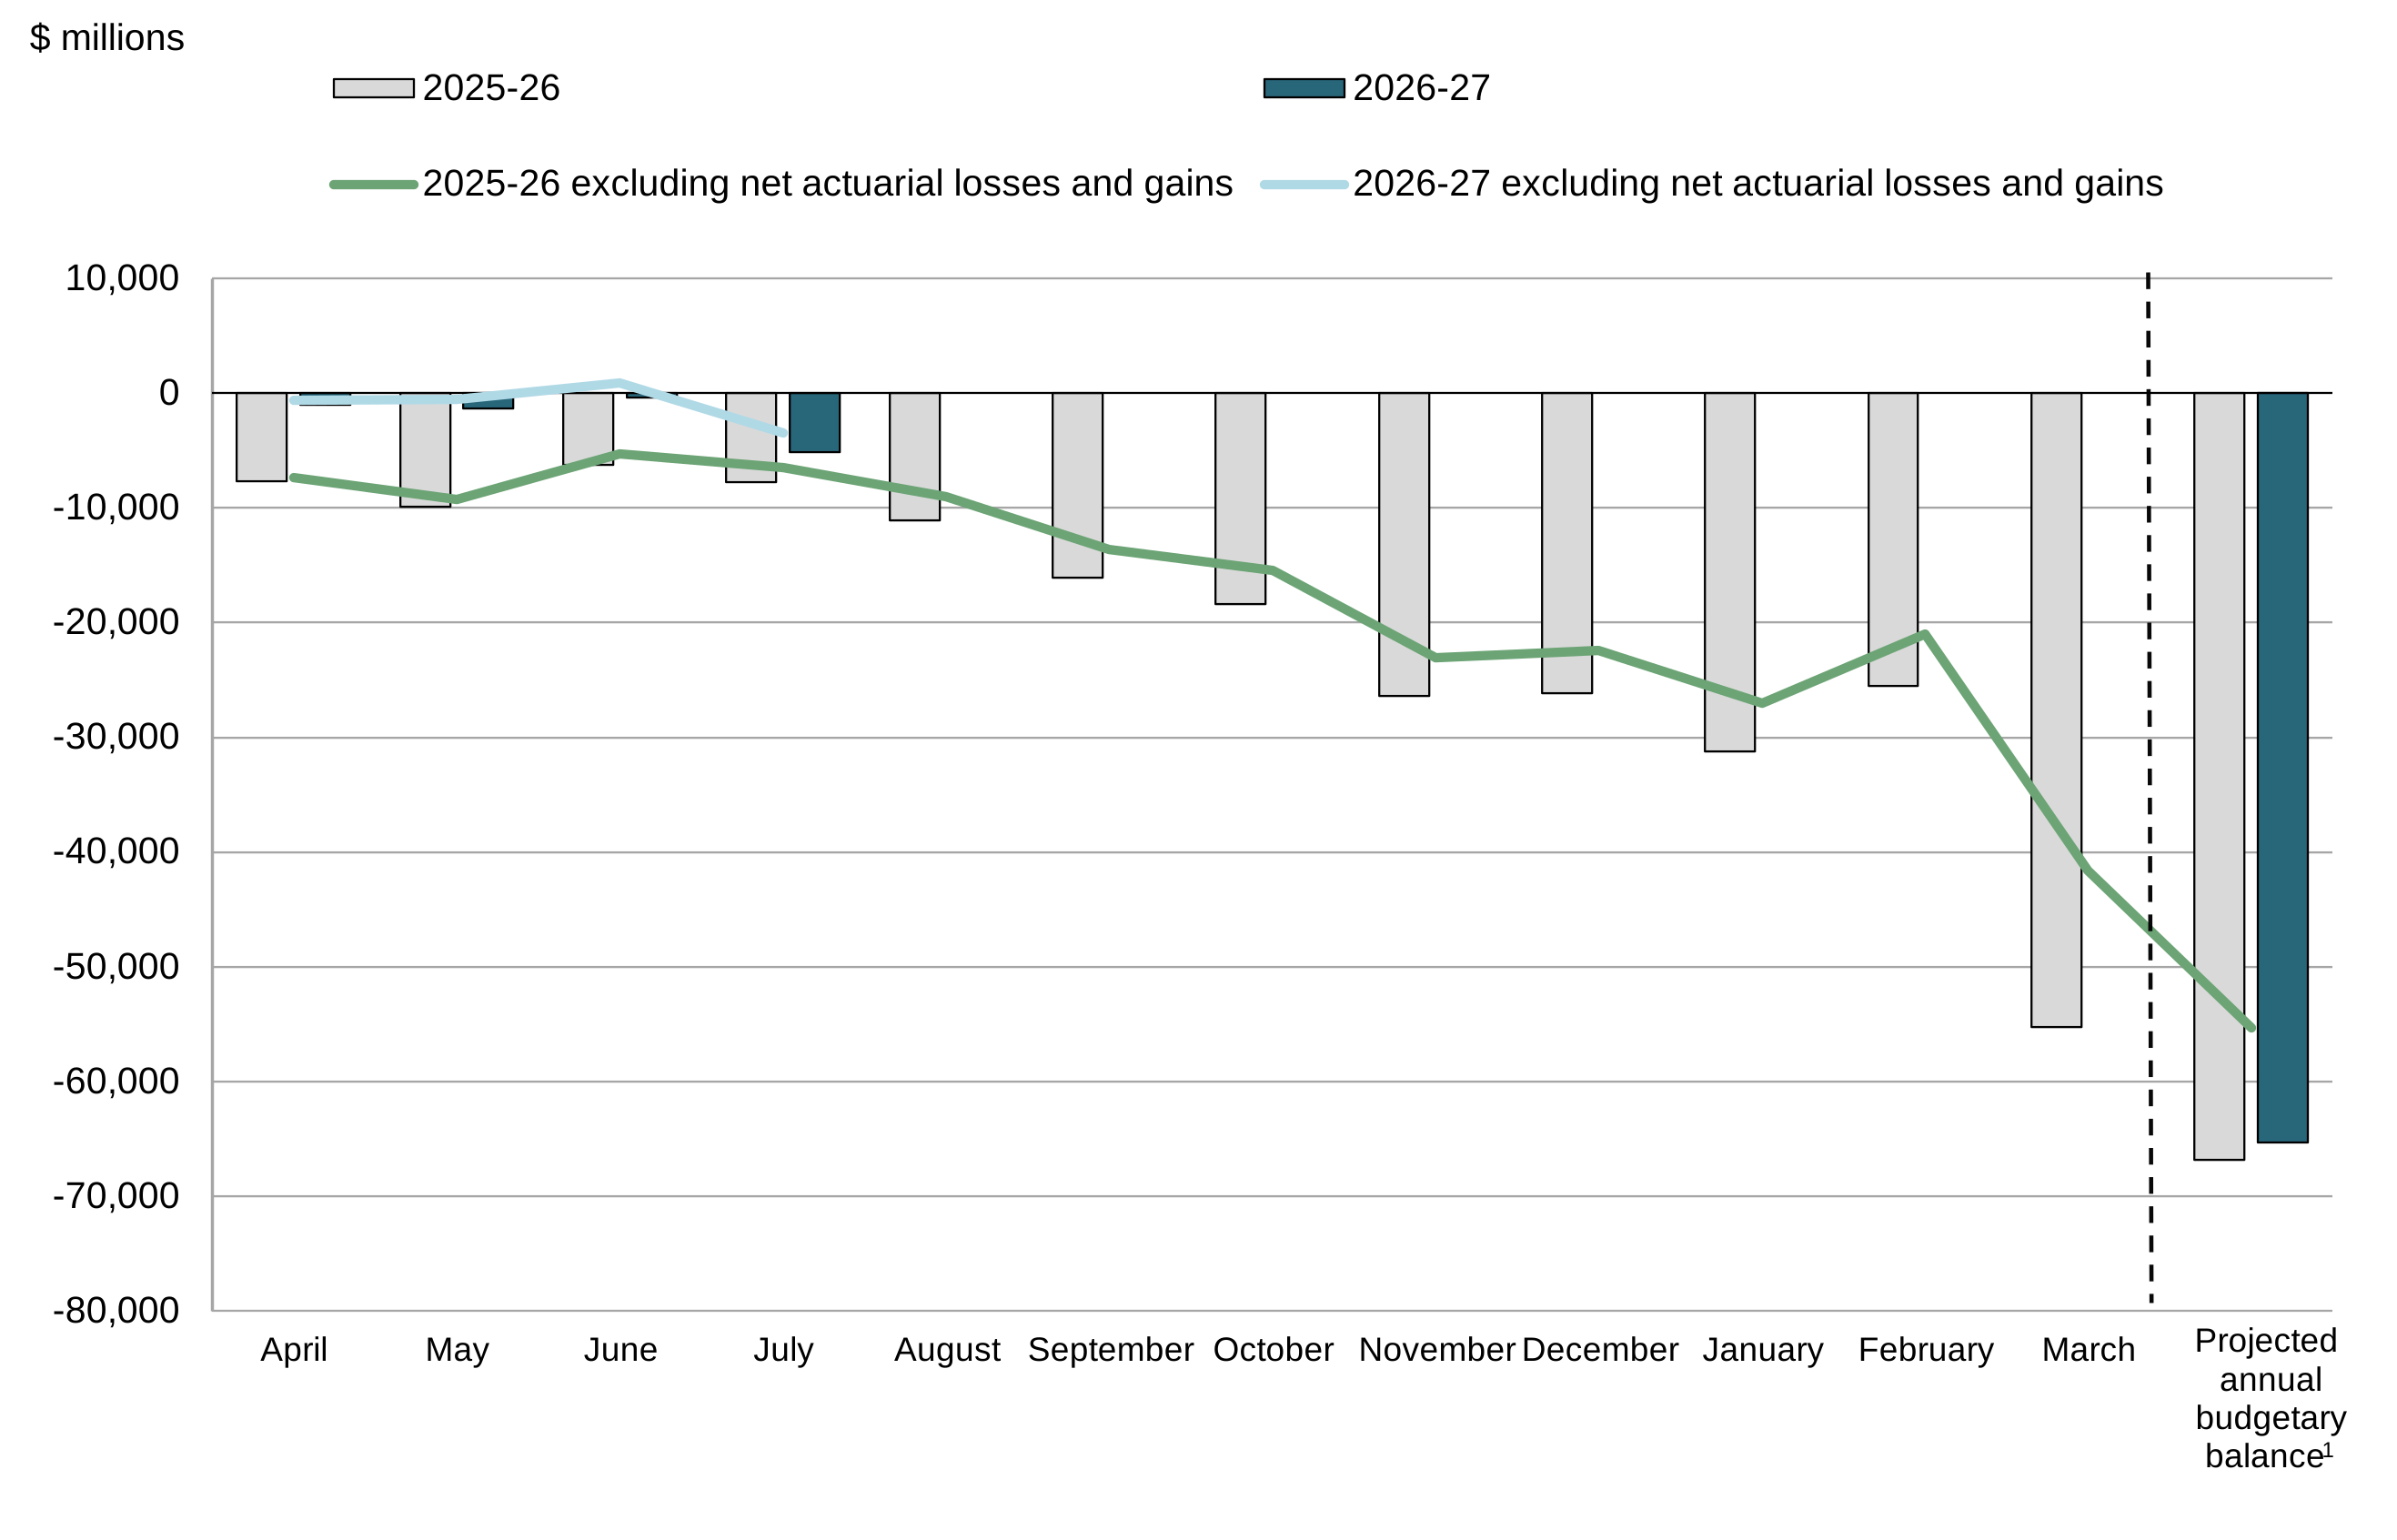
The government posted a budgetary deficit of $5.1 billion for the April to July period of the 2026-27 fiscal year, compared to a deficit of $7.8 billion reported for the same period of 2025-26. The budgetary deficit before net actuarial losses was $3.5 billion, compared to a deficit of $6.4 billion in the April to July period of 2025-26.
Compared to 2025-26:
- Revenues were up $12.0 billion, or 7.4 per cent, largely reflecting increases in personal income tax revenues, other revenues and GST revenues. These increases were offset in part by lower customs import duties, energy tax revenues and corporate income tax revenues.
- Program expenses excluding net actuarial losses were up $7.7 billion, or 5.1 per cent, due mainly to increases in direct program expenses and major transfers to persons, offset in part by lower pollution pricing proceeds returned to Canadians.
- Public debt charges increased by $1.4 billion, or 7.4 per cent, largely reflecting higher average effective interest rates on an increased stock of marketable bonds and higher Consumer Price Index adjustments on Real Return Bonds, offset in part by lower short-term interest rates on treasury bills.
- Net actuarial losses increased by $0.3 billion, or 23.9 per cent, reflecting the amortization of losses arising from actuarial valuations of the government's pension and other employee future benefit plans as at March 31, 2025, which began partway through 2025-26, offset in part by the end of the amortization of certain prior years' net actuarial losses.
Year-to-Date Budgetary Balance and Budgetary Balance Excluding Net Actuarial Losses and Gains
| July | April to July | |||
|---|---|---|---|---|
| 2025 | 2026 | 2025-26 | 2026-27 | |
| Budgetary transactions | ||||
|
Revenues
|
42,607 | 42,825 | 163,443 | 175,469 |
|
Expenses
|
||||
|
Program expenses, excluding net actuarial losses
|
-38,959 | -41,807 | -151,293 | -158,968 |
|
Public debt charges
|
-4,825 | -5,371 | -18,597 | -19,979 |
| Budgetary balance, excluding net actuarial losses | -1,177 | -4,353 | -6,447 | -3,478 |
|
Net actuarial losses
|
-335 | -415 | -1,340 | -1,660 |
| Budgetary balance (deficit/surplus) | -1,512 | -4,768 | -7,787 | -5,138 |
| Non-budgetary transactions | -9,291 | -10,475 | -33,545 | -49,584 |
| Financial source/requirement | -10,803 | -15,243 | -41,332 | -54,722 |
| Net change in financing activities | 31,048 | 28,511 | 68,042 | 59,553 |
| Net change in cash balances | 20,245 | 13,268 | 26,710 | 4,831 |
| Cash balance at end of period | 72,850 | 53,168 | ||
| Note: Positive numbers indicate net source of funds. Negative numbers indicate net requirement for funds. | ||||
Revenues
Revenues in July 2026 totalled $42.8 billion, up $0.2 billion, or 0.5 per cent, from July 2025.
- Tax revenues decreased by $0.8 billion, or 2.3 per cent, reflecting lower corporate income tax revenues, lower customs import duties following the repeal of countermeasures imposed in response to U.S. tariffs, and lower energy tax revenues due to the fuel excise tax relief measures introduced in April 2026. These decreases were partially offset by higher personal income tax and GST revenues.
- Employment Insurance (EI) premium revenues were up $0.1 billion, or 2.9 per cent, reflecting a higher number of persons employed and the increase in maximum insurable earnings that took effect January 1, 2026.
- Other revenues were up $1.0 billion, or 21.9 per cent, largely due to higher interest and penalties revenues, as well as higher revenues from enterprise Crown corporations.
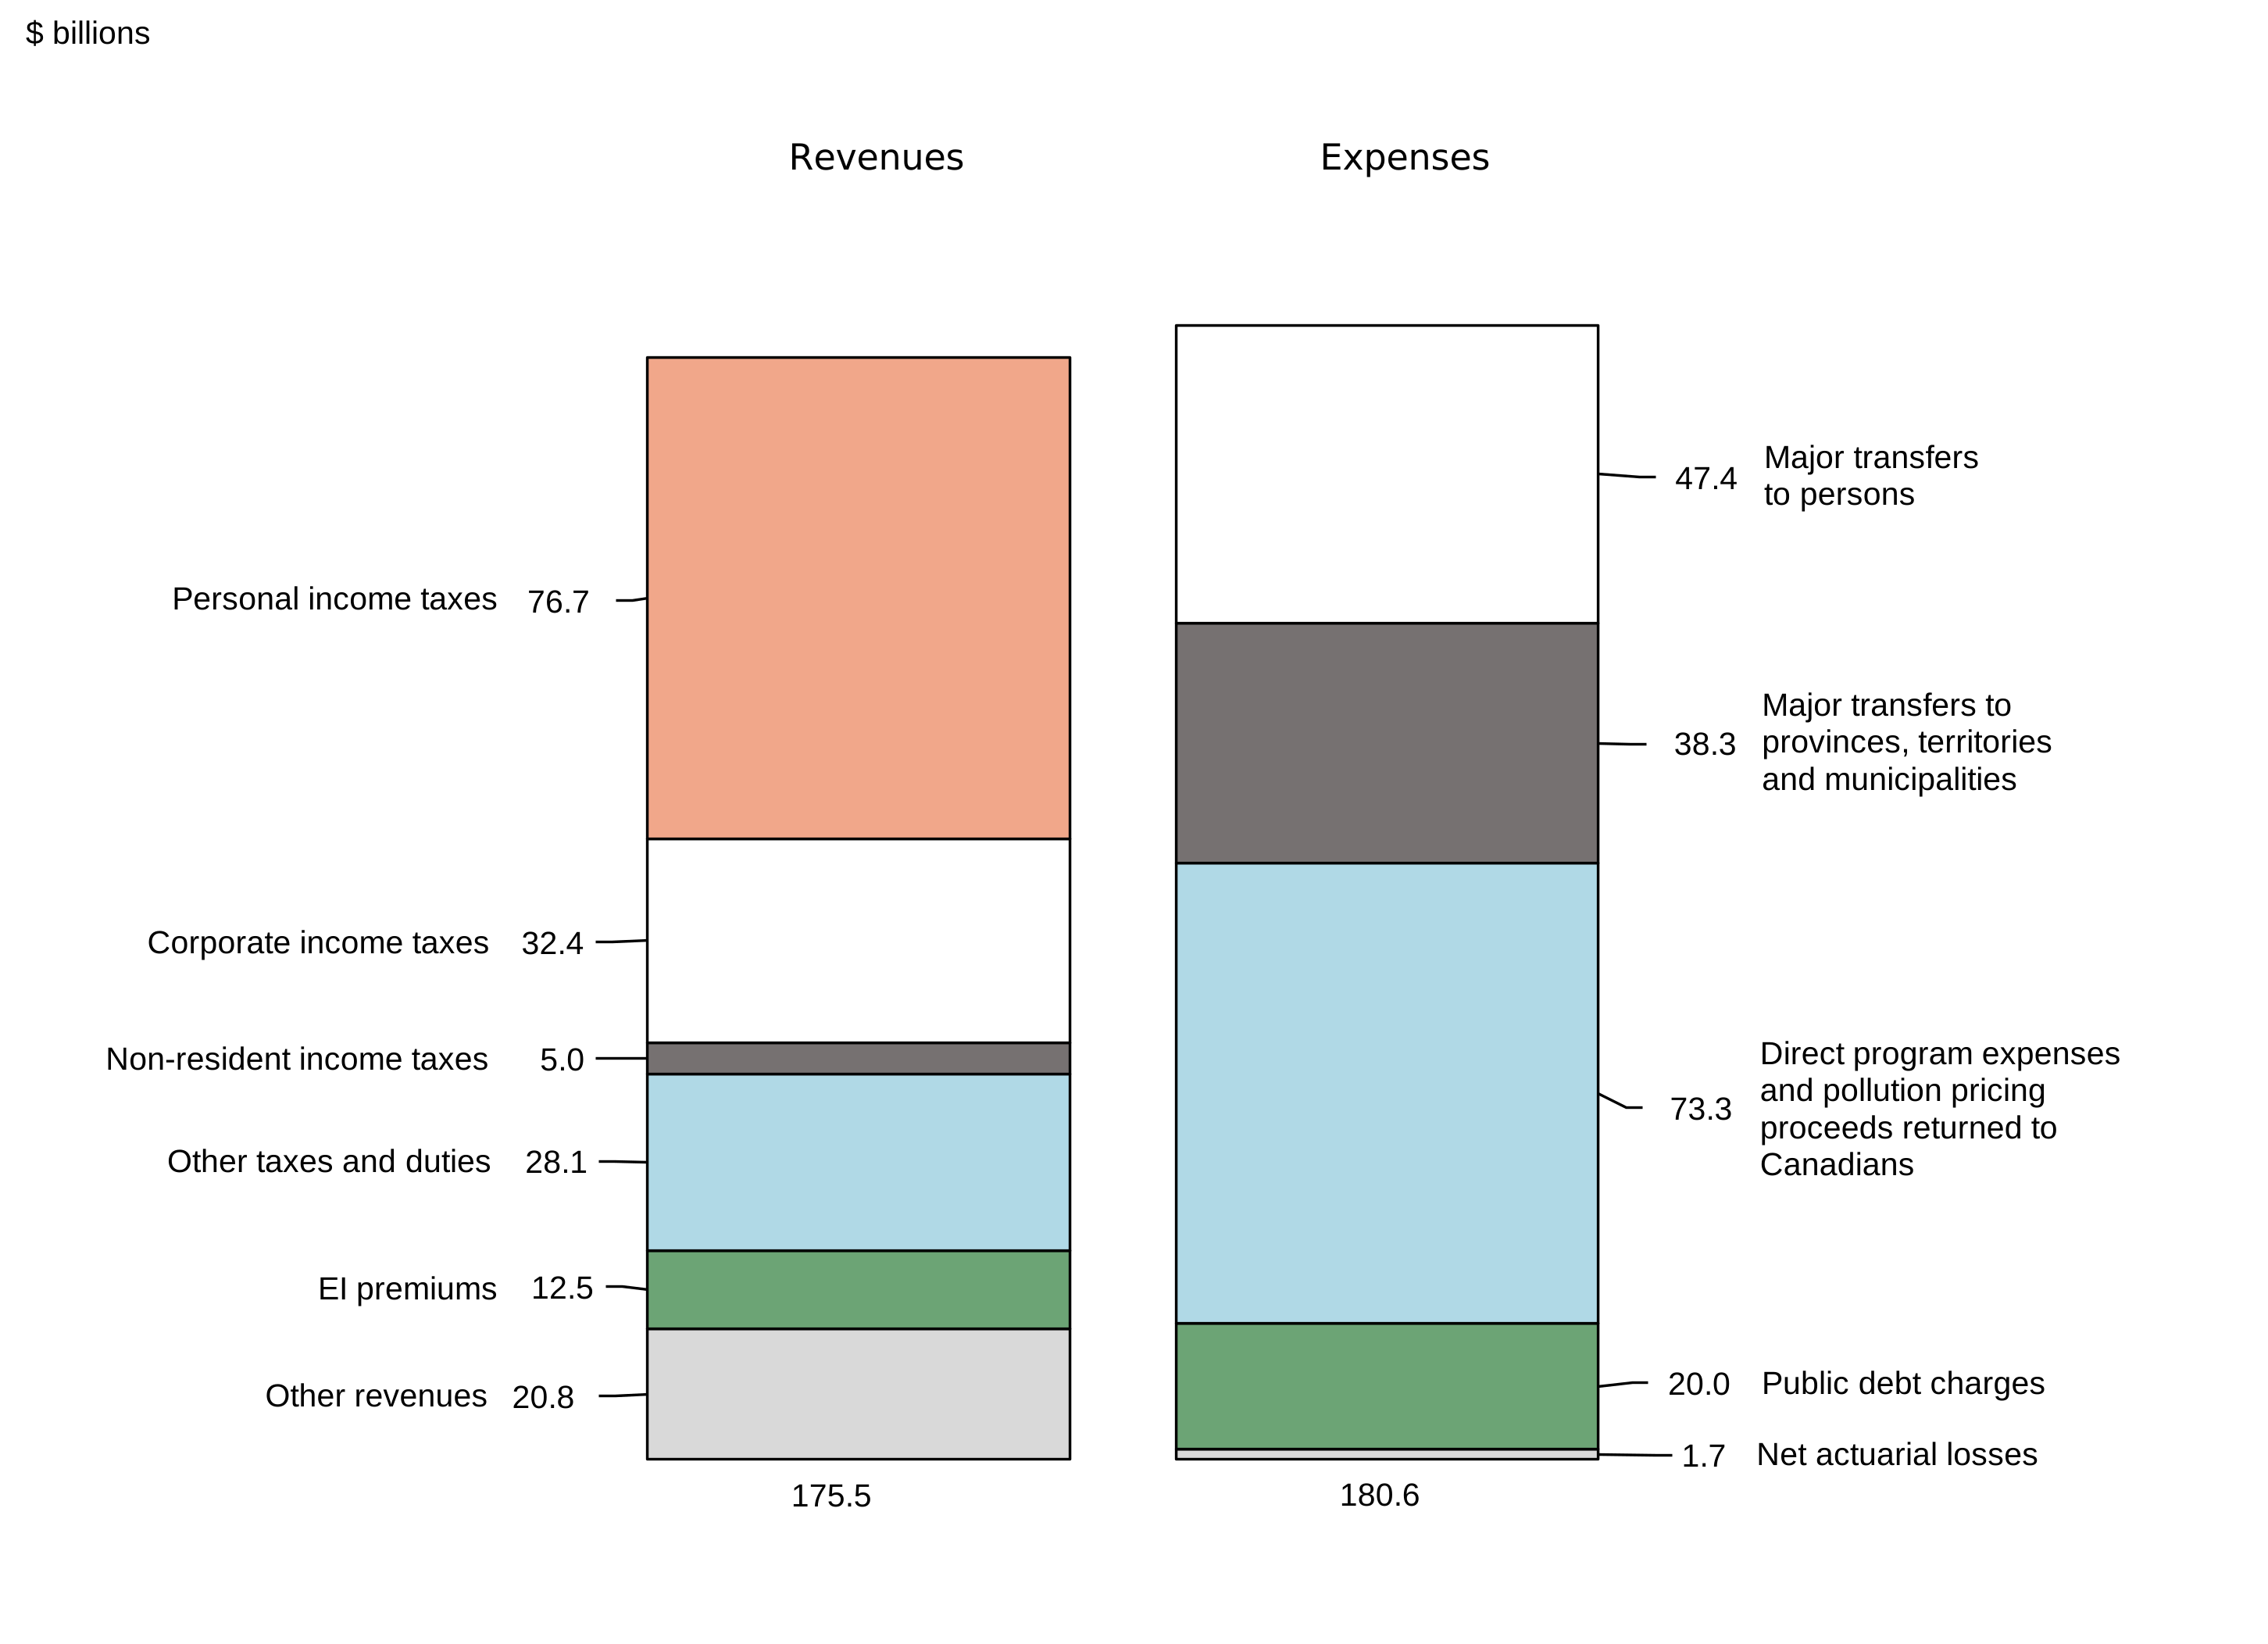
Revenues for the April to July period of 2026-27 totalled $175.5 billion, up $12.0 billion, or 7.4 per cent, from the same period in 2025-26.
- Tax revenues increased by $6.1 billion, or 4.4 per cent, compared to the same period in 2025-26, reflecting increases in personal income taxes, driven by higher wages and salaries and an increase in employment, and higher GST revenues following a return to more historically comparable levels after unusually low revenues in early 2025-26. These increases were partially offset by lower customs import duties, energy tax revenues and corporate income tax revenues.
- EI premium revenues were up $0.7 billion, or 5.8 per cent, reflecting a higher number of persons employed and the increase in maximum insurable earnings that took effect January 1, 2026.
- Other revenues were up $5.3 billion, or 34.1 per cent, due in large part to higher interest and penalties revenues, as well as higher revenues from enterprise Crown corporations and offshore resource revenues.
| July | April to July | |||||
|---|---|---|---|---|---|---|
| 20251 | 2026 | Change | 2025-261 | 2026-27 | Change | |
| ($ millions) | (%) | ($ millions) | (%) | |||
| Tax revenues | ||||||
|
Income taxes
|
||||||
|
Personal
|
17,121 | 18,480 | 7.9 | 71,037 | 76,679 | 7.9 |
|
Corporate
|
9,323 | 7,817 | -16.2 | 32,810 | 32,416 | -1.2 |
|
Non-resident
|
1,419 | 1,343 | -5.4 | 4,516 | 4,980 | 10.3 |
|
Total income tax revenues
|
27,863 | 27,640 | -0.8 | 108,363 | 114,075 | 5.3 |
|
Other taxes and duties
|
||||||
|
Goods and Services Tax
|
5,366 | 5,895 | 9.9 | 18,853 | 21,476 | 13.9 |
|
Energy taxes
|
478 | -19 | -104.0 | 1,786 | 1,265 | -29.2 |
|
Customs import duties
|
1,096 | 518 | -52.7 | 4,663 | 2,925 | -37.3 |
|
Other taxes, excise taxes and duties
|
657 | 605 | -7.9 | 2,471 | 2,446 | -1.0 |
|
Total other taxes and duties
|
7,597 | 6,999 | -7.9 | 27,773 | 28,112 | 1.2 |
|
Total tax revenues
|
35,460 | 34,639 | -2.3 | 136,136 | 142,187 | 4.4 |
| Employment Insurance premiums | 2,780 | 2,861 | 2.9 | 11,825 | 12,514 | 5.8 |
| Other revenues | 4,367 | 5,325 | 21.9 | 15,482 | 20,768 | 34.1 |
| Total revenues | 42,607 | 42,825 | 0.5 | 163,443 | 175,469 | 7.4 |
Note: Totals may not add due to rounding. 1 Certain comparative figures have been reclassified to reflect the current year's presentation. In particular, pollution pricing proceeds to be returned to Canadians is included in other revenues. This reflects the cessation of the application of the federal fuel charge effective April 1, 2025. |
||||||
Expenses
Program expenses excluding net actuarial losses in July 2026 were $41.8 billion, up $2.8 billion, or 7.3 per cent, from July 2025.
- Major transfers to persons, consisting of the Old Age Security program, EI benefits, and children's benefits, were up $0.6 billion or 4.9 per cent.
- Transfers through the Old Age Security program increased by $0.4 billion, or 6.0 per cent, reflecting growth in the number of recipients and changes in consumer prices, to which benefits are fully indexed.
- EI benefits increased by $0.1 billion, or 3.1 per cent, largely reflecting new measures that expanded access to EI benefits.
- Children's benefits were up $0.1 billion, or 3.5 per cent, in part reflecting the indexation of benefits to consumer prices, which annually takes effect July 1st.
- Major transfers to provinces, territories and municipalities were up $1.0 billion, or 10.1 per cent, mainly reflecting a year-over-year difference in the timing of Canada-wide Early Learning and Child Care transfers and legislated growth in the Canada Health Transfer, the Canada Social Transfer, Equalization transfers and transfers to the territories.
- Pollution pricing proceeds returned to Canadians increased by $0.1 billion, or 53.8 per cent. Residual payments continue as part of the broader structural wind-down of fuel charge return mechanisms following the removal of the federal fuel charge on April 1, 2025.
- Direct program expenses were up $1.3 billion, or 7.0 per cent. Within direct program expenses:
- Other transfer payments decreased by $0.1 billion, or 1.6 per cent.
- Operating expenses of the government's departments, agencies, and consolidated Crown corporations and other entities increased by $1.4 billion, or 12.9 per cent. This increase was driven in large part by a change in the methodology for recording bad debt expense associated with taxes receivable introduced in December 2025, which has resulted in the recording of an estimate of the expenses throughout the current fiscal year rather than in the post-March period, and increased defence spending.
Public debt charges increased $0.5 billion, or 11.3 per cent, largely reflecting higher average effective interest rates on an increased stock of marketable bonds and higher Consumer Price Index adjustments on Real Return Bonds, offset in part by lower interest rates on treasury bills.
Net actuarial losses, which represent the amortization of changes in the value of the government's obligations for pensions and other employee future benefits accrued in previous fiscal years and related assets, were up $0.1 billion, or 23.9 per cent, reflecting the amortization of losses arising from actuarial valuations of the government's pension and other employee future benefit plans prepared for the Public Accounts of Canada 2025, which began partway through 2025-26, offset in part by the end of the amortization of certain prior years' net actuarial losses.
For the April to July period of 2026-27, program expenses excluding net actuarial losses were $159.0 billion, up $7.7 billion, or 5.1 per cent, from the same period the previous year.
- Major transfers to persons were up $2.3 billion or 5.1 per cent.
- Transfers through the Old Age Security program increased by $1.4 billion, or 5.2 per cent, reflecting growth in the number of recipients and changes in consumer prices, to which benefits are fully indexed.
- EI benefits increased by $0.5 billion, or 6.0 per cent, largely reflecting new measures that expanded access to EI benefits.
- Children's benefits were up $0.4 billion, or 3.9 per cent, in part reflecting the indexation of benefits to consumer prices.
- Major transfers to provinces, territories and municipalities were down $0.2 billion, or 0.5 per cent, as legislated growth in the Canada Health Transfer, the Canada Social Transfer, Equalization transfers and transfers to the territories was more than offset by year-over-year differences in the timing of health care transfers and Canada-wide early learning and child care transfers.
- Pollution pricing proceeds returned to Canadians decreased by $2.1 billion, or 85.5 per cent, reflecting the structural wind-down of the Canada Carbon Rebate for individuals and other fuel charge return mechanisms following the removal of the federal fuel charge effective April 1, 2025.
- Direct program expenses were up $7.7 billion, or 11.8 per cent. Within direct program expenses:
- Other transfer payments increased by $3.2 billion, or 12.4 per cent, reflecting higher transfers in a number of areas, including defence contributions, the Canada Workers Benefit, transfers in respect of Indigenous Peoples, offshore resource revenue transfers, and the Canadian Dental Care Plan.
- Operating expenses of the government's departments, agencies, and consolidated Crown corporations and other entities increased by $4.5 billion, or 11.4 per cent, largely attributable to a change in the methodology for recording bad debt expense associated with taxes receivable, which has resulted in the recording of expenses earlier in the fiscal year, higher personnel costs, and increased defence spending.
Public debt charges increased by $1.4 billion, or 7.4 per cent, largely reflecting higher average effective interest rates on an increased stock of marketable bonds and higher Consumer Price Index adjustments on Real Return Bonds, offset in part by lower short-term interest rates on treasury bills.
Net actuarial losses were up by $0.3 billion, or 23.9 per cent, reflecting the amortization of losses arising from actuarial valuations of the government's pension and other employee future benefit plans as at March 31, 2025, which began partway through 2025-26, offset in part by the end of the amortization of certain prior years' net actuarial losses.
| July | April to July | |||||
|---|---|---|---|---|---|---|
| 20251 | 2026 | Change | 2025-261 | 2026-27 | Change | |
| ($ millions) | (%) | ($ millions) | (%) | |||
| Major transfers to persons | ||||||
|
Old Age Security program
|
6,833 | 7,242 | 6.0 | 27,043 | 28,459 | 5.2 |
|
Employment Insurance benefits
|
2,160 | 2,226 | 3.1 | 8,351 | 8,855 | 6.0 |
|
Children's benefits
|
2,346 | 2,428 | 3.5 | 9,743 | 10,119 | 3.9 |
|
Total major transfers to persons
|
11,339 | 11,896 | 4.9 | 45,137 | 47,433 | 5.1 |
| Major transfers to provinces, territories and municipalities | ||||||
|
Canada Health Transfer
|
4,557 | 4,785 | 5.0 | 18,228 | 19,145 | 5.0 |
|
Canada Social Transfer
|
1,451 | 1,495 | 3.0 | 5,805 | 5,980 | 3.0 |
|
Equalization
|
2,181 | 2,263 | 3.8 | 8,723 | 9,053 | 3.8 |
|
Territorial Formula Financing
|
373 | 397 | 6.4 | 2,503 | 2,665 | 6.5 |
|
Canada-wide early learning and child care
|
548 | 1,034 | 88.7 | 2,416 | 2,049 | -15.2 |
|
Build Communities Strong Fund - Community Stream
|
1,095 | 1,224 | 11.8 | 1,095 | 1,224 | 11.8 |
|
Health agreements with provinces/territories2
|
- | - | n/a | 2,150 | 909 | -57.7 |
|
Other fiscal arrangements3
|
-649 | -677 | -4.3 | -2,454 | -2,761 | -12.5 |
|
Total major transfers to provinces, territories and municipalities
|
9,556 | 10,521 | 10.1 | 38,466 | 38,264 | -0.5 |
| Pollution pricing proceeds returned to Canadians | 132 | 203 | 53.8 | 2,469 | 357 | -85.5 |
| Direct program expenses | ||||||
|
Other transfer payments
|
7,282 | 7,164 | -1.6 | 26,080 | 29,319 | 12.4 |
|
Operating expenses
|
10,650 | 12,023 | 12.9 | 39,141 | 43,595 | 11.4 |
|
Total direct program expenses
|
17,932 | 19,187 | 7.0 | 65,221 | 72,914 | 11.8 |
| Total program expenses, excluding net actuarial losses | 38,959 | 41,807 | 7.3 | 151,293 | 158,968 | 5.1 |
| Public debt charges | 4,825 | 5,371 | 11.3 | 18,597 | 19,979 | 7.4 |
| Total expenses, excluding net actuarial losses | 43,784 | 47,178 | 7.8 | 169,890 | 178,947 | 5.3 |
|
Net actuarial losses
|
335 | 415 | 23.9 | 1,340 | 1,660 | 23.9 |
| Total expenses | 44,119 | 47,593 | 7.9 | 171,230 | 180,607 | 5.5 |
Note: Totals may not add due to rounding. 1 Certain comparative figures have been reclassified to reflect the current year's presentation. In particular, COVID-19 income support for workers is included in other transfer payments, reflecting the end of temporary COVID-19 support measures. In addition, certain other amounts have been reclassified from operating expenses and from major transfers to provinces, territories and municipalities to other transfer payments to align with their expected presentation in the Public Accounts of Canada. 2 Health agreements with provinces and territories include the Working Together bilateral agreements and Aging with Dignity bilateral agreements. Remaining funding under the Home and Community Care, and Mental Health and Addictions Services bilateral agreements was integrated into these agreements. 3 Other fiscal arrangements include the Quebec Abatement (Youth Allowances Recovery and Alternative Payments for Standing Programs), which represents an ongoing recovery from Quebec associated with a historical tax point transfer; statutory subsidies; and other items. With respect to the Quebec Abatement - Alternative Payments for Standing Programs, transfers to Quebec for the Canada Health Transfer, Canada Social Transfer and Equalization are shown above on the same basis as transfers to other provinces. However, since part of the Quebec transfer is made through abated federal taxes, it is necessary to net this amount out of major transfers to provinces, territories and municipalities. The remaining portion of the Quebec Abatement reflects recoveries for the tax points transferred for the discontinued Youth Allowances program. |
||||||
The following table presents total expenses by main object of expense.
| July | April to July | |||||
|---|---|---|---|---|---|---|
| 20251 | 2026 | Change | 2025-261 | 2026-27 | Change | |
| ($ millions) | (%) | ($ millions) | (%) | |||
| Transfer payments | 28,309 | 29,784 | 5.2 | 112,152 | 115,373 | 2.9 |
| Other expenses | ||||||
|
Personnel, excluding net actuarial losses
|
6,274 | 6,467 | 3.1 | 24,309 | 25,688 | 5.7 |
|
Transportation and communications
|
239 | 302 | 26.4 | 791 | 923 | 16.7 |
|
Information
|
46 | 26 | -43.5 | 120 | 115 | -4.2 |
|
Professional and special services
|
1,739 | 2,024 | 16.4 | 4,816 | 6,087 | 26.4 |
|
Rentals
|
503 | 541 | 7.6 | 1,879 | 1,984 | 5.6 |
|
Repair and maintenance
|
295 | 406 | 37.6 | 888 | 1,072 | 20.7 |
|
Utilities, materials and supplies
|
217 | 294 | 35.5 | 950 | 1,207 | 27.1 |
|
Other subsidies and expenses
|
850 | 1,495 | 75.9 | 3,344 | 4,645 | 38.9 |
|
Amortization of tangible capital assets
|
471 | 454 | -3.6 | 1,993 | 1,839 | -7.7 |
|
Net loss on disposal of assets
|
16 | 14 | -12.5 | 51 | 35 | -31.4 |
|
Total other expenses
|
10,650 | 12,023 | 12.9 | 39,141 | 43,595 | 11.4 |
| Total program expenses, excluding net actuarial losses | 38,959 | 41,807 | 7.3 | 151,293 | 158,968 | 5.1 |
| Public debt charges | 4,825 | 5,371 | 11.3 | 18,597 | 19,979 | 7.4 |
| Total expenses, excluding net actuarial losses | 43,784 | 47,178 | 7.8 | 169,890 | 178,947 | 5.3 |
|
Net actuarial losses
|
335 | 415 | 23.9 | 1,340 | 1,660 | 23.9 |
| Total expenses | 44,119 | 47,593 | 7.9 | 171,230 | 180,607 | 5.5 |
Note: Totals may not add due to rounding. 1 Certain comparative figures have been reclassified to reflect the current year's presentation. |
||||||
Revenues and expenses (April to July 2026)
Financial requirement of $54.7 billion for April to July 2026
The budgetary balance is presented on an accrual basis of accounting, recording government revenues and expenses when they are earned or incurred, regardless of when the cash is received or paid. In contrast, the financial source/requirement measures the difference between cash coming in to the government and cash going out. This measure is affected not only by changes in the budgetary balance but also by the cash source/requirement resulting from the government's investing activities through its acquisition of capital assets and its loans, financial investments and advances, as well as from other activities, including payment of accounts payable and collection of accounts receivable, foreign exchange activities, and the amortization of its tangible capital assets. The difference between the budgetary balance and financial source/requirement is recorded in non-budgetary transactions.
With a budgetary deficit of $5.1 billion and a requirement of $49.6 billion from non-budgetary transactions, there was a financial requirement of $54.7 billion for the April to July 2026 period, compared to a financial requirement of $41.3 billion for the same period of the previous year.
| July | April to July | |||
|---|---|---|---|---|
| 2025 | 2026 | 2025-26 | 2026-27 | |
| Budgetary balance (deficit/surplus) | -1,512 | -4,768 | -7,787 | -5,138 |
| Non-budgetary transactions | ||||
|
Accounts payable, accrued liabilities and accounts receivable
|
-4,180 | -5,678 | -16,479 | -27,038 |
|
Pensions, other future benefits, and other liabilities
|
95 | 262 | 2,242 | 2,532 |
|
Foreign exchange accounts and derivatives
|
-1,328 | -772 | 2,412 | -1,356 |
|
Loans, investments and advances
|
-2,071 | -3,127 | -18,510 | -20,273 |
|
Non-financial assets
|
-1,807 | -1,160 | -3,210 | -3,449 |
|
Total non-budgetary transactions
|
-9,291 | -10,475 | -33,545 | -49,584 |
| Financial source/requirement | -10,803 | -15,243 | -41,332 | -54,722 |
| Note: Totals may not add due to rounding. | ||||
Net financing activities up $59.6 billion
The government financed this financial requirement of $54.7 billion and increased cash balances by $4.8 billion by increasing unmatured debt by $59.6 billion. The increase in unmatured debt was achieved through the issuance of marketable bonds and treasury bills.
Cash balances at the end of July 2026 stood at $53.2 billion, down $19.7 billion from their level at the end of July 2025.
| July | April to July | |||
|---|---|---|---|---|
| 2025 | 2026 | 2025-26 | 2026-27 | |
| Financial source/requirement | -10,803 | -15,243 | -41,332 | -54,722 |
| Net increase (+)/decrease (-) in financing activities | ||||
|
Unmatured debt transactions
|
||||
|
Canadian currency borrowings
|
||||
|
Marketable bonds
|
26,178 | 20,638 | 55,324 | 37,711 |
|
Treasury bills
|
3,795 | 7,969 | 18,530 | 23,309 |
|
Total Canadian currency borrowings
|
29,973 | 28,607 | 73,854 | 61,020 |
|
Foreign currency borrowings
|
1,096 | -73 | -5,901 | -1,345 |
|
Total market debt transactions
|
31,069 | 28,534 | 67,953 | 59,675 |
|
Obligations related to capital leases and other unmatured debt
|
-21 | -23 | 89 | -122 |
| Net change in financing activities | 31,048 | 28,511 | 68,042 | 59,553 |
| Change in cash balance | 20,245 | 13,268 | 26,710 | 4,831 |
| Cash balance at end of period | 72,850 | 53,168 | ||
| Note: Totals may not add due to rounding. | ||||
Notes
- The Fiscal Monitor is a report on the consolidated financial results of the Government of Canada, prepared monthly by the Department of Finance Canada. The government is committed to releasing The Fiscal Monitor on a timely basis in accordance with the International Monetary Fund's Special Data Dissemination Standards Plus, which are designed to promote member countries' data transparency and promote the development of sound statistical systems.
- The financial results reported in The Fiscal Monitor are drawn from the accounts of Canada, which are maintained by the Receiver General and used to prepare the annual Public Accounts of Canada.
- The Fiscal Monitor is generally prepared in accordance with the same accounting policies as used to prepare the government's annual consolidated financial statements, which are summarized in Section 2 of Volume I of the Public Accounts of Canada, available through the Public Services and Procurement Canada website.
- The financial results presented in The Fiscal Monitor have not been audited or reviewed by an external auditor.
- There can be substantial volatility in monthly results due to the timing of revenue receipts and expense recognition. For instance, a large share of government spending is typically reported in the March Fiscal Monitor.
- The April to March results reported in The Fiscal Monitor are not the final results for the fiscal year as a whole. The final results are published in the annual Public Accounts of Canada and incorporate post-March end-of-year adjustments made once further information becomes available, including the accrual of tax revenues reflecting assessments of tax returns and valuation adjustments for assets and liabilities. Post-March adjustments may also include the accrual of measures announced in the budget that are recorded upon receipt of Royal Assent of enabling legislation.
- Table 7, Condensed Statement of Assets and Liabilities, is included in the monthly Fiscal Monitor following the finalization and publication of the government's financial results for the preceding fiscal year, typically in the fall.
Note: Unless stated otherwise, changes in financial results are presented on a year-over-year basis.
For inquiries about this publication, contact Gina Clark at gina.clark@fin.gc.ca.
September 2026